Private equity vs venture capital comes down to what the business already is. Private equity firms mostly back established, profitable businesses, often buying control and using borrowed money to fund the purchase. Venture capital funds take minority stakes in young businesses that aren’t yet profitable but could grow very large, very fast.
Both are funds that invest other people’s money in private companies and sell their stake a few years later. I’ve funded more than 750 businesses with over £1bn and invested in more than 100, so I’ve seen both kinds of deal as an investor, as a lender and as the founder on the other side of the table.
The Difference Between Private Equity and Venture Capital
The UK’s industry body for both, UK Private Capital, formerly the BVCA, describes private equity as finance that typically backs buyouts of mature companies, where the investors generally own a controlling stake. It describes venture capital as investment in early-stage businesses, many not yet making a profit, where the funds take minority stakes, often alongside other investors.
In the US, private equity and venture capital have separate trade bodies, the American Investment Council and the National Venture Capital Association. In the Dubai International Financial Centre, the regulator’s fund rules have a separate category for venture capital funds, and in Singapore the government’s Startup SG Equity scheme co-invests alongside private investors in technology startups.
| Private equity | Venture capital | |
|---|---|---|
| Businesses it backs | Established, usually profitable, with steady cash flow | Young, often pre-profit, with the potential to grow very large |
| Typical stake | Majority in a buyout; minority in a growth deal | Minority, usually alongside other investors |
| Where the money goes | Mostly to the existing owners in a buyout; into the company in a growth deal | Into the company, to fund growth |
| Use of debt | Often borrows against the business to help fund the purchase | Little or none |
| Control | Board control and day-to-day influence in a buyout | A board seat and consent rights over major decisions |
| How it makes its return | Profit growth, paying down debt and selling at a higher value | A few very large exits that cover the losses on the rest |
| Holding period | Typically 4 to 7 years | Typically 5 to 7 years |
| Usual exit | Sale to a trade buyer, another private equity firm or a listing | Sale to a larger company or a stock market listing |
For a founder raising for the first time, the PE vs VC question often sits alongside a different one, covered in angel investors vs venture capitalists.
Stage and Business Type Each Backs
A venture fund has to return several times what it raised within a fixed life, and it expects many of its investments to be written off. That only works if a few of them return 100 times or more, so a venture fund only backs businesses that could become enormous. In practice that means sectors where a business can grow without its costs growing at the same rate, such as software, technology and life sciences.
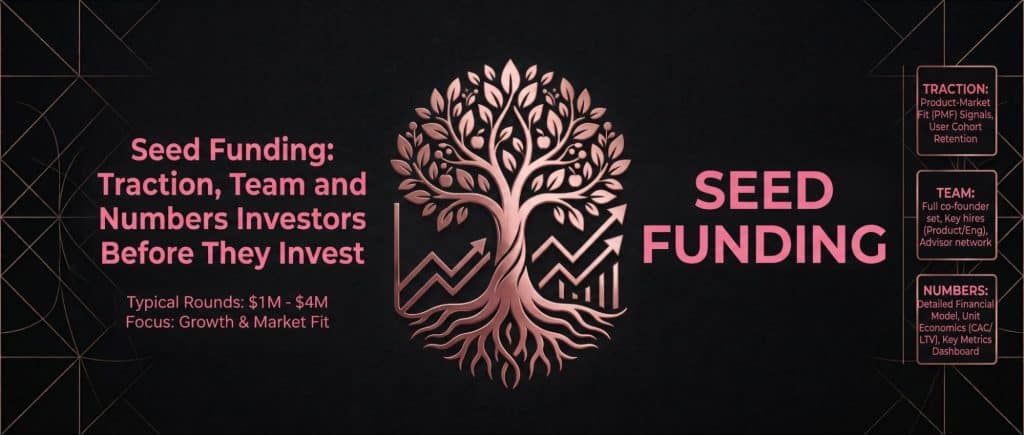
Venture rounds have names that follow the business’s progress. The first outside money is often a pre-seed round, followed by seed, where investors look at the traction, team and numbers, and then Series A, the first large round from venture funds.
Private equity backs businesses that have already proved themselves. A typical target has years of trading, reliable profits and cash flow it can predict, in almost any sector. The business doesn’t have to be growing fast. A steady business with room to grow by buying competitors, opening new sites or improving margins can suit a private equity firm well.
Between the two sits growth equity. It’s money for a business that’s already profitable or close to it and wants to grow faster, usually as a minority stake. Some venture funds and many private equity firms do this kind of deal. In the UK, the British Business Bank’s Small Business Equity Tracker found that investment in growth-stage smaller businesses rose 10% to £5.7bn in 2025.
Control: Minority vs Majority Stakes
A venture fund buys a minority stake and the founders keep running the business. Because a minority holding on its own gives an investor very little say, a venture fund putting in a large sum usually wants rights on top of its shares, written into the shareholders’ agreement and the company’s articles:
- a seat on the board, so it’s in the room for every significant decision
- consent rights over a list of decisions, such as raising more money, taking on debt, selling the business or changing the share structure
- information rights, meaning regular management accounts and an annual budget
- protection if a later round is raised at a lower price, known as anti-dilution protection
A private equity buyout is different. The firm buys more than half of the shares, and with them the right to appoint the board, approve the budget, change the strategy and, if it decides to, replace the managers. The founder who stays on usually keeps a stake and runs the business day to day, but they now report to a board the private equity firm controls.
Private equity doesn’t always mean control. Many private equity deals are minority investments, where the firm buys less than half of the shares and the founder keeps the biggest holding. In those deals the firm protects its money with a board seat and consent rights, as a venture fund does.
How the Deals Are Structured
In a venture round, the company issues new shares and the investor pays for them. The money goes into the business to pay for growth, and the founder doesn’t receive any of it. Venture funds usually take preference shares, which carry a liquidation preference: the investor is paid back first when the business is sold, before the ordinary shareholders.
Venture funds use little or no borrowing. In the US, a fund that wants to be treated as a venture capital fund under SEC rules can’t borrow more than 15% of its capital, and only for up to 120 days.
In a private equity buyout, the firm buys existing shares from the owners, so most of the money goes to them rather than into the company. The purchase is usually funded partly with the fund’s own money and partly with debt that a bank or other lender secures against the business being bought. The business then repays that debt from its own profits, and the layering of debt and equity is called a capital stack.
The fund often puts much of its money in as loan notes or preference shares, which are paid out before the ordinary shares, alongside a smaller amount of ordinary shares shared with the management team.
The founder in a buyout is often asked to reinvest part of the sale proceeds in the new company. This is called rolling over. It keeps the founder committed to the business and gives them a second payout when the private equity firm sells.
Say a business makes £2m a year in profit before interest, tax, depreciation and amortisation, known as EBITDA, and both kinds of investor agree it’s worth £12m, 6 times that profit. Here’s how each deal works on the day it completes.
| Private equity buyout | Venture capital round | |
|---|---|---|
| Value of the business before the deal | £12m | £12m (the pre-money valuation) |
| New money from the investor | £5.6m of equity | £3m for new shares |
| Borrowing | £5m from a lender, secured on the business | None |
| Founder’s reinvested equity | £1.4m | None |
| Total funding | £12m, all used to buy the shares | £3m, all paid into the company |
| Cash the founder takes out | £10.6m (£12m less the £1.4m reinvested) | Nothing |
| Founder’s stake afterwards | 20% | 80% |
| Investor’s stake afterwards | 80% | 20% |
| Who controls the board | The private equity firm | The founder, with an investor seat |
In the venture round, the business is worth £15m after the money goes in, and the investor owns 20%, which is £3m divided by £15m. In the buyout, the founder banks £10.6m on day one and owns 20% of a business that now carries £5m of debt.
What Each Wants at Exit
Both kinds of fund have a fixed life, often around 10 years, and both need to sell their stakes and return the money to the people who invested in the fund before it ends. The UK industry body puts the typical holding period at 4 to 7 years for private equity and 5 to 7 years for venture capital.
A venture fund needs a very large exit, usually a sale to a bigger company or a stock market listing. Because it has to cover the losses on the investments that fail, a modest sale that would suit the founder can be too small to matter to the fund. That’s also when the liquidation preference matters most: on a modest sale, the investor’s preference is paid first and the founder can end up with less than their percentage suggested.
A private equity firm makes its return in three ways: growing the profit, paying down the debt so more of the business’s value belongs to the shareholders, and selling at a higher valuation than it paid. Buyers include trade buyers, meaning larger companies in the same sector, other private equity firms and the stock market.
A valuation is a number from today multiplied by a story from tomorrow.
Matt Haycox
Carry on the buyout example. Say that over 5 years the business grows its profit to £3m and pays its debt down to £2m, and it sells at the same multiple of 6 times profit, for £18m.
After repaying the £2m of debt, the shareholders share £16m. The founder’s 20% is worth £3.2m on top of the £10.6m they took at the start, and the fund’s 80% is worth £12.8m against the £5.6m it put in.
In a real deal the fund’s loan notes or preference shares are paid out before the ordinary shares, so the founder’s share can be smaller than the percentage suggests. The price at both ends depends on how your business gets valued, which for an established business is often a multiple of its profit.
The timing can clash with what the founder wants. A founder who plans to run the business for another 20 years and an investor who needs to sell inside 5 or 6 years will want different things, so the exit timetable and what happens if it slips are best agreed in the term sheet.
Which One Fits Your Business
The facts of the business usually decide which kind of investor will be interested, and the founder’s own plans decide which deal they’d accept.
- Does the business make reliable profits? If it does, private equity will look at it. If it doesn’t yet, and needs money to get there, venture capital or angel investors are the likelier route.
- Could it become very large, very fast? Venture funds need businesses that could return many times the fund’s money. A profitable business growing steadily won’t fit a venture fund.
- Does the founder want to take money out? A buyout pays the owners for their shares. A venture round puts money into the company and pays the founder nothing.
- Does the founder want to keep control? A venture round or a minority growth deal leaves the founder in charge, with investor consent rights. A buyout hands control to the private equity firm.
- Can the business carry debt? A buyout loads borrowing onto the business, which has to be paid from its profits.
- When does the founder want to sell? Both kinds of fund will need to sell within a few years. A founder who never wants to sell may be better suited to investors with no fixed exit date, such as a family office, or to borrowing. There’s more on that choice in debt vs equity.
A growing, profitable business that wants money for an acquisition without giving up control can often raise it as a minority growth deal from either kind of investor.
FAQs
Is private equity the same as venture capital?
No, although venture capital is often described as a type of private equity, because both invest in private companies. In practice, private equity usually means investing in established, profitable businesses, often through buyouts, and venture capital means minority investments in young businesses with high growth potential.
Does private equity always take control of a business?
No. Buyouts give the private equity firm control, but many private equity deals are minority growth investments where the founder keeps the biggest holding and runs the business. The firm protects its money with a board seat and consent rights over major decisions.
Do private equity firms invest in startups?
Rarely. Private equity firms usually look for businesses with a track record of profits they can lend against and grow. Startups without profits tend to raise from angel investors and venture capital funds.
Why do private equity firms use debt?
Private equity firms use debt so they put in less of their own money for the same business, which increases the return on what they invest if the business does well. The debt is secured on the business being bought and paid back from its own profits.
Next read
If you run a 7 or 8-figure business and you’re weighing up an approach from private equity or venture capital, the Inner Circle puts you in a room with founders, deal-makers and investors who’ve done these deals from both sides, and with me. If you’d rather work through a specific offer one to one, that’s what my consulting is for.
This is general information about how these deals work, not investment advice.