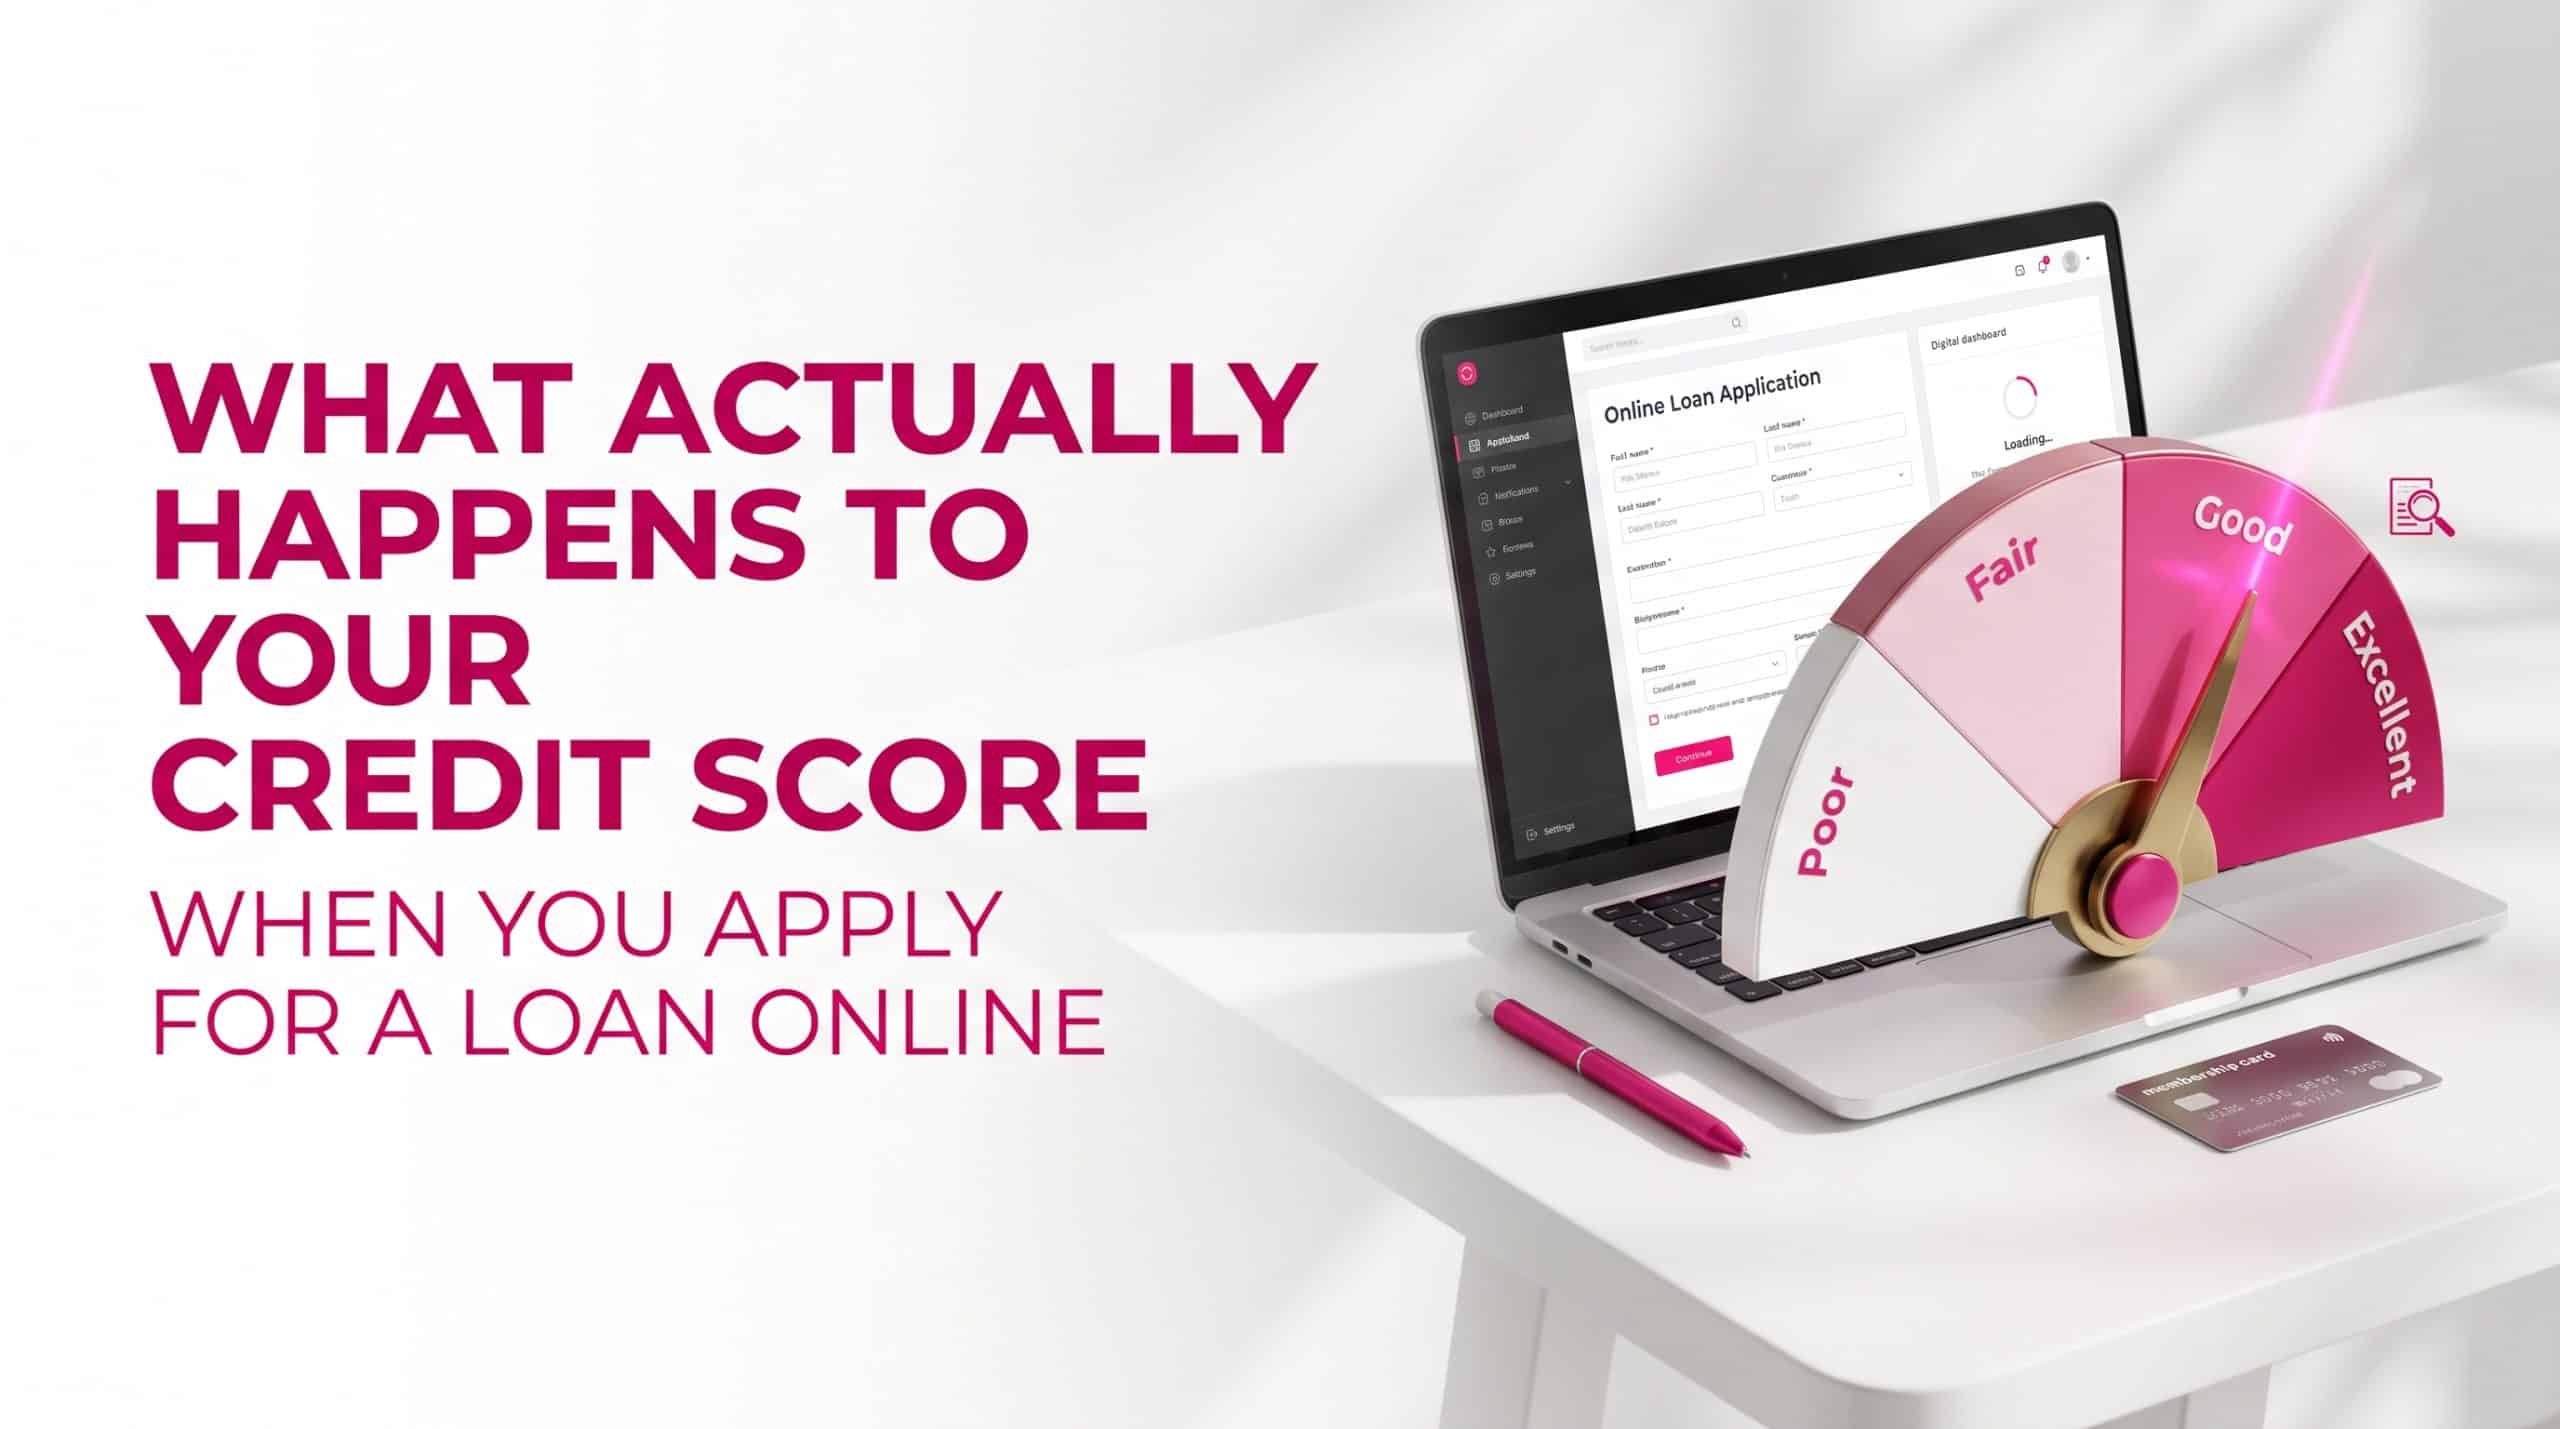
Applying for a loan online has become a popular option due to its convenience and speed. With quick loans accessible at the click of a button, many borrowers are eager to take advantage of the streamlined process. However, potential applicants often wonder what impact, if any, this may have on their credit score. Understanding how online loan applications affect credit reports is essential before making a financial commitment. While the application process itself may seem straightforward, the credit checks involved can influence your financial profile in both the short and long term.
Understanding Credit Scores and Their Importance
A credit score is a numerical representation of an individual’s creditworthiness, based on an analysis of their credit files. It helps lenders evaluate how reliably someone has managed borrowing in the past and how likely they are to repay future debts. A higher score generally indicates better creditworthiness, making it easier to get approved for loans and potentially access more favourable interest rates and repayment terms.
Credit scores are influenced by several factors, including payment history, outstanding debts, the length of credit history, the types of credit accounts held and recent applications for credit. Although different credit reference agencies use different scoring systems, the underlying information is broadly similar.
Maintaining a healthy credit score is important because it can affect more than just loan applications. Credit cards, mortgages, mobile phone contracts and other financial agreements may also involve credit assessments. Understanding what influences your score can help you make better borrowing decisions and avoid unnecessary financial difficulties.
Types of Credit Checks: Soft vs Hard Inquiries
When you apply for a loan, lenders typically perform a credit check, which can be a soft or hard inquiry. Understanding the difference between the two is particularly important when comparing online lending options.
A soft inquiry, also known as a soft search, occurs when you check your own credit report or when a lender assesses your eligibility for certain offers. These checks do not affect your credit score and are not visible to other lenders in the same way as formal applications. This means you can often explore potential borrowing options without worrying about damaging your credit profile.
Conversely, a hard inquiry, or hard search, is generally performed when you formally apply for credit. It allows lenders to review your credit history in greater detail before making a lending decision. Hard searches are recorded on your credit report and may be visible to other lenders.
Not every online loan application automatically involves a hard search. Some providers initially use soft searches to assess eligibility and only carry out a hard search when you proceed with a full application. Checking a lender’s policy before submitting your details can help you understand what to expect.
The Immediate Impact on Your Credit Score
Applying for a loan online may result in a hard inquiry by the lender. This can cause a small temporary decrease in your credit score, although the exact impact depends on your individual credit history and the scoring model being used.
While even a minor reduction might seem concerning, a single hard inquiry is generally not a major factor in determining your overall creditworthiness. Lenders also consider your repayment history, current borrowing levels, income and other financial information when assessing an application.
It is also important to remember that a hard search does not guarantee loan approval. A lender may decline an application even after completing a credit check. In this situation, the inquiry may still appear on your credit report, despite you not receiving the requested funds.
In the UK, hard searches can generally remain visible on your credit report for up to two years, although their influence on lending decisions and credit scoring usually decreases over time.
Long-term Effects of Applying for Loans Online
In the long term, repeatedly applying for loans online can raise questions for potential lenders. Several hard inquiries within a relatively short period may suggest that someone is actively seeking additional credit or experiencing financial pressure.
This does not automatically mean that an application will be rejected. However, lenders may view frequent credit applications as a sign of increased borrowing risk, particularly when combined with high outstanding balances or missed payments.
On the other hand, successfully managing a new loan can contribute positively to your financial history. Making repayments on time demonstrates that you can handle credit responsibly. Over time, consistent payment behaviour can strengthen your credit profile and help establish a positive borrowing record.
However, taking out a loan solely to improve your credit score is rarely a good strategy. Borrowing should always be based on a genuine financial need and your ability to meet the repayment obligations. Interest charges, fees and additional debt can outweigh any potential benefit to your credit history.
Tips for Managing Loan Applications Effectively
Before applying for a loan online, it is sensible to review your credit report and make sure all the information is accurate. Check for outdated details, unfamiliar accounts, incorrect balances or missed payments that may have been recorded by mistake. If you identify an error, contact the relevant credit reference agency to request an investigation.
You should also compare lenders and understand their application procedures before submitting your details. Look for providers that offer eligibility checks using soft searches, allowing you to explore your options without immediately triggering a hard inquiry.
Another useful approach is to avoid submitting multiple applications at once. Instead, research your options carefully, compare interest rates and repayment periods, and choose a lender that matches your financial circumstances.
Finally, consider whether the monthly repayments fit comfortably within your budget. Account for essential expenses, existing financial commitments and unexpected costs. Choosing a realistic repayment schedule can reduce the risk of missed payments, which can have a much more significant impact on your credit score than a single hard inquiry.
Final Thoughts
Applying for a loan online does not necessarily mean damaging your credit score. Although a formal application may trigger a hard credit search and cause a small temporary decrease, the long-term effect largely depends on how you manage your borrowing.
By understanding the difference between soft and hard searches, comparing lenders carefully and keeping up with repayments, you can make more confident financial decisions. The convenience of online lending can be useful, but taking time to understand the potential consequences will help you protect your credit history and maintain greater control over your finances.